
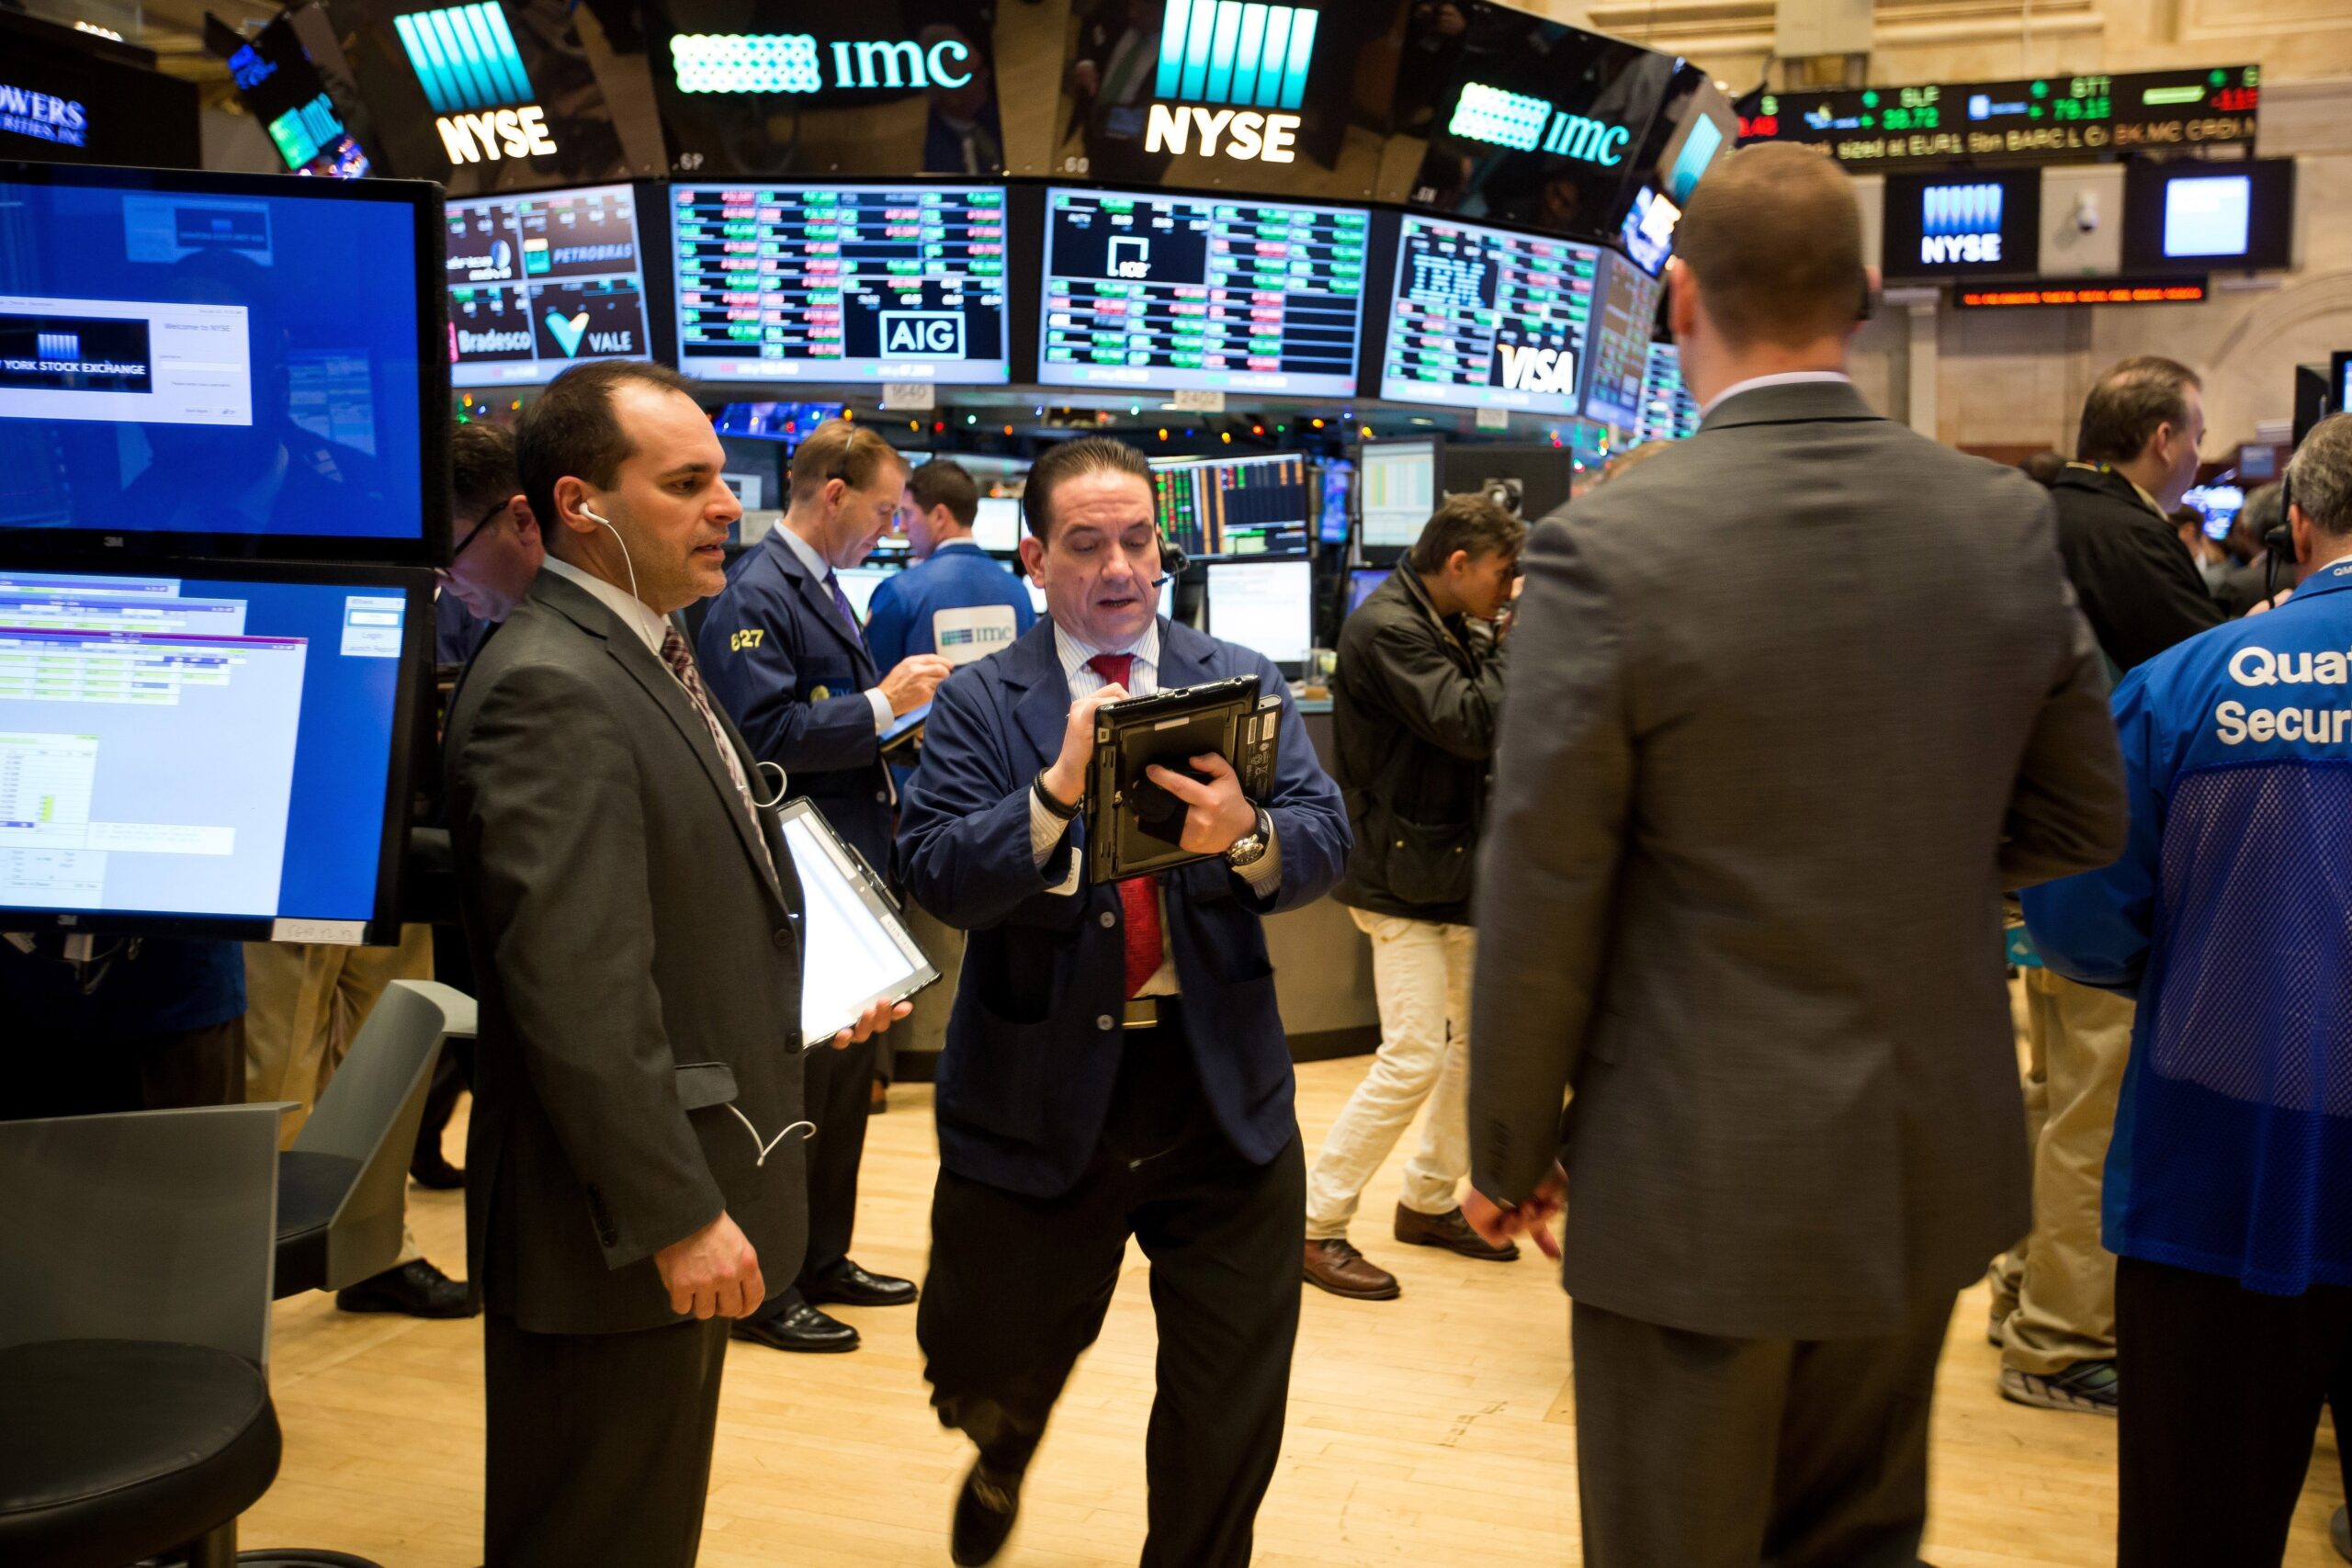
US stock futures moved higher on Wednesday evening after Wall Street recorded one of its strongest sessions in months. A sharp fall in oil prices and greater certainty about the results of the 2026 midterm elections helped improve investor sentiment.
Futures linked to the Dow Jones Industrial Average gained 90 points, or 0.2%. S&P 500 futures rose 0.1%, while Nasdaq-100 futures remained almost unchanged.
The movement followed a broad rally during Wednesday’s regular trading session. Investors responded to falling energy costs and the news that Democrats had secured control of both chambers of Congress. The party also won several important governorships.
The Dow Jones Industrial Average climbed more than 1,500 points, marking a gain of around 3%. It was the index’s strongest daily performance since April 2025. The S&P 500 also advanced, rising 1.6%.
Oil prices played a major role in the market’s recovery. West Texas Intermediate crude futures dropped more than 8% and settled at $88.12 per barrel. The decline eased some concerns about energy costs and their possible impact on businesses and consumers.
The fall in oil prices came as investors continued to assess the economic effects of the Iran war. Vice President JD Vance blamed the conflict for Republican losses in Tuesday’s midterm elections. His comments added to market attention on the connection between foreign policy, energy prices and political decisions.
Individual company results also influenced trading after the closing bell. Qualcomm reported earnings that exceeded market expectations. However, its shares fell 6.5% in after-hours trading.
AppLovin had a stronger reaction. The artificial intelligence-powered advertising company surged almost 24% after reporting better-than-expected results and providing a financial outlook above analyst estimates.
The different share price movements showed that strong earnings do not always lead to immediate gains. Investors also consider future expectations, company valuations and the outlook for individual industries.
During Wednesday’s regular session, consumer-focused companies helped support the wider market. Walmart shares gained more than 3%, making the retailer one of the notable performers among consumer discretionary stocks.
However, some companies connected to the rapid expansion of data centers faced selling pressure. CoreWeave was among the businesses affected by concerns about possible political resistance to new data center projects.
Election results in several states have increased attention on the environmental and economic impact of large data center developments. In Texas, Democratic candidate Gina Hinojosa won the governor’s race after calling for stricter limits on data center construction.
The result raised questions about future rules for companies investing heavily in artificial intelligence infrastructure. Data centers require large amounts of electricity, land and other resources. As a result, their expansion has become an important issue in several local and state political debates.
Jordan Watson, a portfolio manager at Tandem Investment Advisors, said Wednesday’s market rally and movement away from some artificial intelligence stocks might not last. He warned that investors could face further uncertainty as they consider the election results and possible policy changes.
Watson said the latest trading should not be treated as a clear signal that market risks have disappeared. Instead, he pointed to the need for investors to examine the large sums being invested in AI infrastructure and whether those projects can deliver the expected financial returns.
International markets showed mixed results on Thursday. Japan’s Nikkei 225 gained 0.49%, while the broader Topix index advanced more than 2%.
South Korea’s Kospi fell 2.33%. The technology-focused Kosdaq also declined, losing 1.24%. Australia’s S&P/ASX 200 moved in the opposite direction and rose 1.39%.
Investors are now preparing for several important economic reports in the United States. Weekly jobless claims data is due on Thursday and could provide fresh information about the condition of the labor market.
The October nonfarm payrolls report is scheduled for Friday. The figures may help investors assess employment trends and the wider economic outlook.
Several major companies are also expected to release earnings on Thursday. Tapestry, Kimberly-Clark and ConocoPhillips are scheduled to report before the market opens. Airbnb and Akamai are expected to publish their results later in the day.
With economic data, corporate earnings and political changes all influencing market expectations, investors may remain cautious despite Wednesday’s strong gains.
